The $900 Billion Question: Inside the AI Infrastructure Race
As Anthropic prepares for a massive public offering, scrutiny turns to the staggering compute costs and the shifting power dynamics between hardware giants and model developers.
By Ricardo Brooks ·
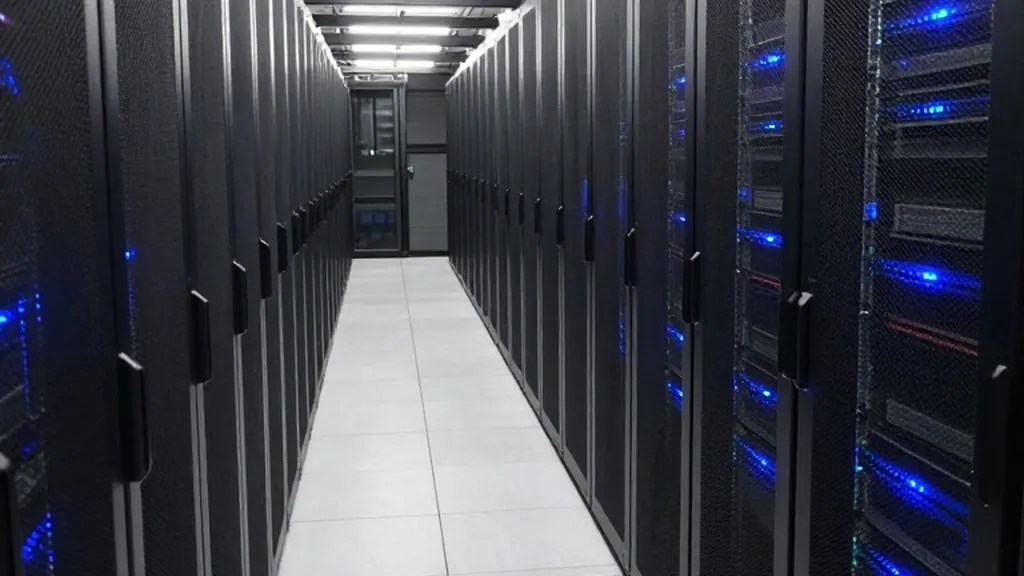
Wall Street has sold the public on a compelling narrative. Artificial intelligence is framed as the greatest investment opportunity of a lifetime. For many, that story holds true. The technology is transforming how people work, learn, and create. Yet a significant disconnect exists between the promise of revolution and the reality of the balance sheets. The companies leading this charge are spending astronomical sums just to keep their systems operational. Infrastructure costs are running into the billions. Competitors are increasingly offering capable tools at lower price points. Meanwhile, the firms controlling the necessary hardware are moving to acquire the platforms that distribute the software. This is a gold rush where valuations are measured in trillions, but the path to profitability remains unclear.
At the center of this debate is Anthropic, the developer behind the Claude model. Early market expectations suggested a potential valuation of $2 trillion or more. However, the company’s IPO pricing proposal, filed on November 10, points to a range of approximately $1.3 trillion to $1.4 trillion. While still an eye-watering figure, it raises a fundamental question for investors and users alike. What exactly are they paying for?
The answer lies in the disclosures. Anthropic’s latest filings reveal approximately $900.9 billion in purchase commitments and lease agreements, largely tied to computing infrastructure. To put that in perspective, nearly nine hundred billion dollars is a sum that few governments have ever committed to a single technology sector. According to the filings, approximately $451.6 billion of this amount is expected to be incurred before the end of 2030. The remainder stretches out through 2045. About $70.7 billion is due within the 12 months following September 30, 2026.
These are not speculative projections by critics. They are contractual obligations stated in the company’s own securities documents. While these commitments are not the same as existing debt, and the full amount is not immediately payable, they represent a massive future financial burden. Anthropic has disclosed substantial liquidity and financing arrangements, so it is not accurate to say the company is already $500 billion in debt. However, the economic pressure is real. How much revenue must the company generate year after year to support an infrastructure strategy of this scale?
Anthropic’s revenue is growing at a rapid pace. Its October annualized revenue run rate reportedly reached approximately $81 billion. This figure is far above the less than $20 billion annual revenue number sometimes cited in casual discussions. But annualized revenue is not annual profit. It is not free cash flow. It is certainly not money that can automatically be used to satisfy hundreds of billions in future commitments. Even if Anthropic eventually generates $100 billion in annual revenue, it must still pay for computing, research, personnel, electricity, facilities, and administration. Revenue is not the finish line. Profitability and sustainable cash generation are. A trillion-dollar valuation requires investors to believe that the company will produce extraordinary profits over many years. That belief might prove correct. But belief is not proof.
To understand the economics, consider the hardware. Let us look at one Nvidia RTX PRO 6000-class GPU. In an illustrative scenario, the retail purchase price is approximately $20,000. Imagine this GPU can serve 15 to 20 light AI users under certain model and workload conditions, generating approximately 60 to 70 tokens per second. Alternatively, it might support one or two intensive coding users running heavy workloads at approximately 40 to 50 tokens per second. These are illustrative assumptions, not universal benchmarks. Actual performance varies depending on model size, context length, and batching efficiency.
Suppose 20 light users each pay $20 monthly. That generates $400 in monthly subscription revenue. At that rate, recovering the cost of a single $20,000 GPU would take 50 months, assuming every dollar of revenue went toward that specific piece of hardware. Now consider two heavy users paying $200 each per month. Again, that is $400 monthly. Again, it takes 50 months to recover the hardware purchase. And that does not include the cost of the server, CPUs, RAM, networking, storage, cooling, electricity, maintenance, or the building itself. It does not include the engineers who keep the system running or the costs of failed hardware and customer support.
The actual economics of a hyperscale AI provider are more sophisticated. Enterprise inference accelerators are not necessarily consumer cards. A single machine can serve many users whose activity is intermittent. Efficient batching and specialized chips can improve utilization. But the underlying concern remains. AI is not free to operate. Subscription revenue alone does not tell us whether a customer is profitable.
What if the GPU cost is lower? Let us be generous. Imagine a hypothetical wholesale cost of just $4,000 per accelerator. At $400 in combined monthly subscription revenue, that still requires 10 months to recover the GPU cost alone. At $3,000, it takes 7.5 months. These are hypothetical prices, not verified contract rates. Factor in depreciation, electricity, and other server components, and the break-even period grows.
The counterargument is that most people do not use AI continuously. A light subscriber might interact with Claude for only a few hours per week, allowing the same hardware to support a much larger paying customer base. That is true, and it is one reason consumer subscriptions can work. But intensive coding agents create a different challenge. They can execute long-running tasks, make repeated tool calls, and generate enormous token volumes. A $200 subscriber using a service occasionally may be highly profitable. A $200 subscriber constantly running demanding coding agents may have very different economics. This is why the most important metric is not simply how many customers an AI company has. It is how much contribution profit each customer produces after the cost of serving them. Until investors can clearly understand those unit economics, extraordinary valuations deserve scrutiny.
There is one company positioned to benefit whether Claude wins, ChatGPT wins, or another model takes the lead. That company is Nvidia. The AI industry requires enormous quantities of accelerators, high-bandwidth memory, and supporting infrastructure. When demand for this equipment exceeds available manufacturing capacity, prices rise and delivery schedules lengthen. Large technology companies can negotiate enormous supply arrangements and reserve capacity years in advance. Smaller developers and independent researchers cannot compete on the same financial terms. The result is an increasingly unequal marketplace. A company with billions of dollars can secure computing infrastructure at a scale that a startup or university researcher could never reasonably match. Nvidia benefits from this imbalance, even if it did not deliberately create every supply shortage.